Budget watchdogs have been given fresh cause for concern this week as the rate on 10-year Treasuries has tipped over 5%—a symbolic benchmark for investors and economists.
At the time of writing, yields on the 10-year note sat at 5.027%, having climbed steadily since February of this year.
The 52-week high came after the U.S. Treasury intervened in the bond market, with a multi-billion-dollar buyback scheme last month in an attempt to improve market liquidity.
But after a brief drop, yields resumed their march higher ahead of this week’s Federal Open Market Committee (FOMC) meeting, and ongoing tensions in the Middle East contributing to inflationary fears.
With yields now notching over 5%, longer-term interest rates across the economy are increasing, pushing up borrowing costs on the national debt as a result. Budget hawks have long worried that the U.S. might enter a debt spiral—a cycle where interest payments cause debt to grow because more borrowing is needed to finance that debt.
As Maya MacGuineas, president of the Committee for a Responsible Federal Budget, said in a statement last night: “If rates remain 80 basis points-plus above projections over the next decade, we’re on course to spend an annual $2.7 trillion on interest payments at the end of the decade. We’ll be spending more on interest than Medicare or Social Security retirement benefits.”
“High interest rates also increase cost-of-living for ordinary Americans. New homebuyers are paying 7% on their mortgages, and other loans are even more expensive. For businesses, the high cost of borrowing may stifle investment, slowing economic growth and leaving Americans poorer than they otherwise would be.”
The “real threat” is a debt spiral, MacGuineas added, saying: “A fiscal crisis, once unthinkable, is now a distinct possibility … If 5% interest rates aren’t a wake-up call, I don’t know what will be.”
Those on the bullish end of the debt debate would point out that, although yields are relatively elevated, the factors driving the rise at present don’t necessarily stem from fiscal concerns. Rather, they may reflect growth or inflation expectations over time, as opposed to demand for higher returns due to perceived risk in holding U.S. debt.
Bulls also argue that the U.S. economy could grow its way out of any fiscal concerns—increased productivity from the AI boom could propel the country out of danger, for instance.
The 5% benchmark
While debt hawks and doves might debate the importance of the 5% threshold being hit, UBS’s Paul Donovan points out that the number actually means very little in a real economic sense.
He told clients this morning: “Economically, there is no significant difference between a 4.9% yield and a 5.0% yield. Politically, 5.0% has more impact, as does the direction of travel. U.S. Treasury Secretary ‘House’ Bessent’s attempts to steer the market have not been crowned in glory, and U.S. fiscal policy has very limited credibility at the moment.”
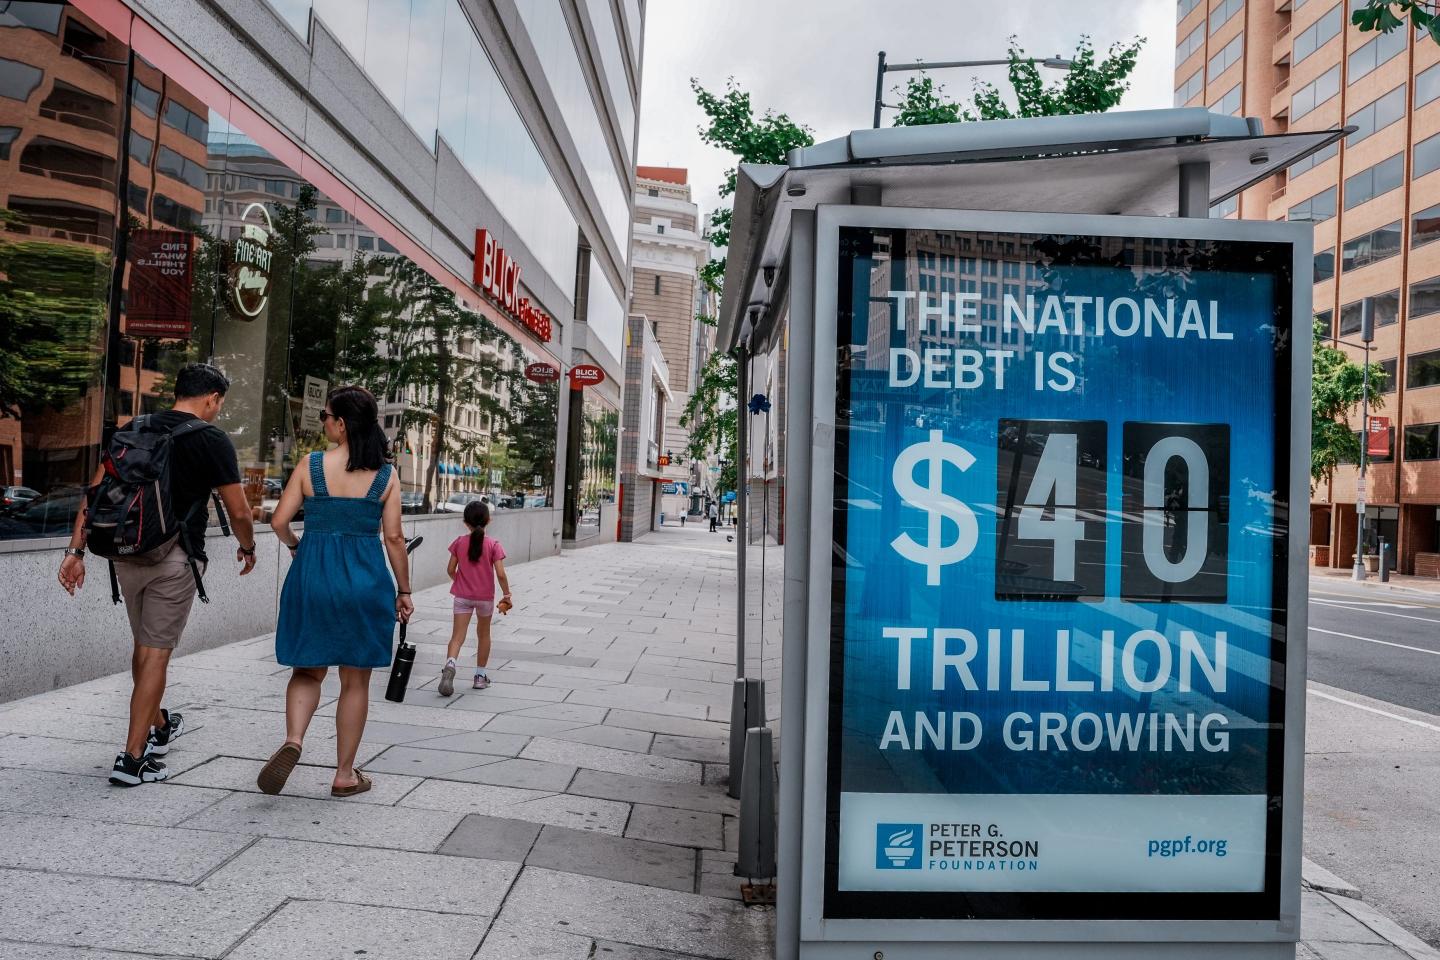
Likewise, Roman Ziruk, lead FX strategist at global financial services firm Ebury, pointed out that while the U.S. is an outlier with its debt at over $40 trillion, rising Treasury yields are not limited to a single nation.
“The ongoing Iran war has fuelled a surge in oil prices, reviving inflation fears and adding a fresh layer of uncertainty as to the path for long-term central bank rates,” Ziruk noted to clients last night. “This is clearly not just a U.S. phenomenon, but a global one. Yields across the major economic areas have all risen in tandem with U.S. Treasuries in recent weeks, pointing to a shared, geopolitically driven pressure on bond markets that is not confined to the U.S. alone.”