In the check-out line of your local grocery store, there’s a nearly one-in-three chance someone there has used an app like Klarna or Affirm to finance their purchase of produce, milk, and eggs at some point. Their use of buy now, pay later could mean your groceries are about to cost more, economists have found.
A study from the University of Washington in St. Louis, which will be published in the next issue of the Management Science journal, found that as more consumers turn to buy now, pay later to purchase their necessities, retailers may actually increase prices and slash inventory as a result.
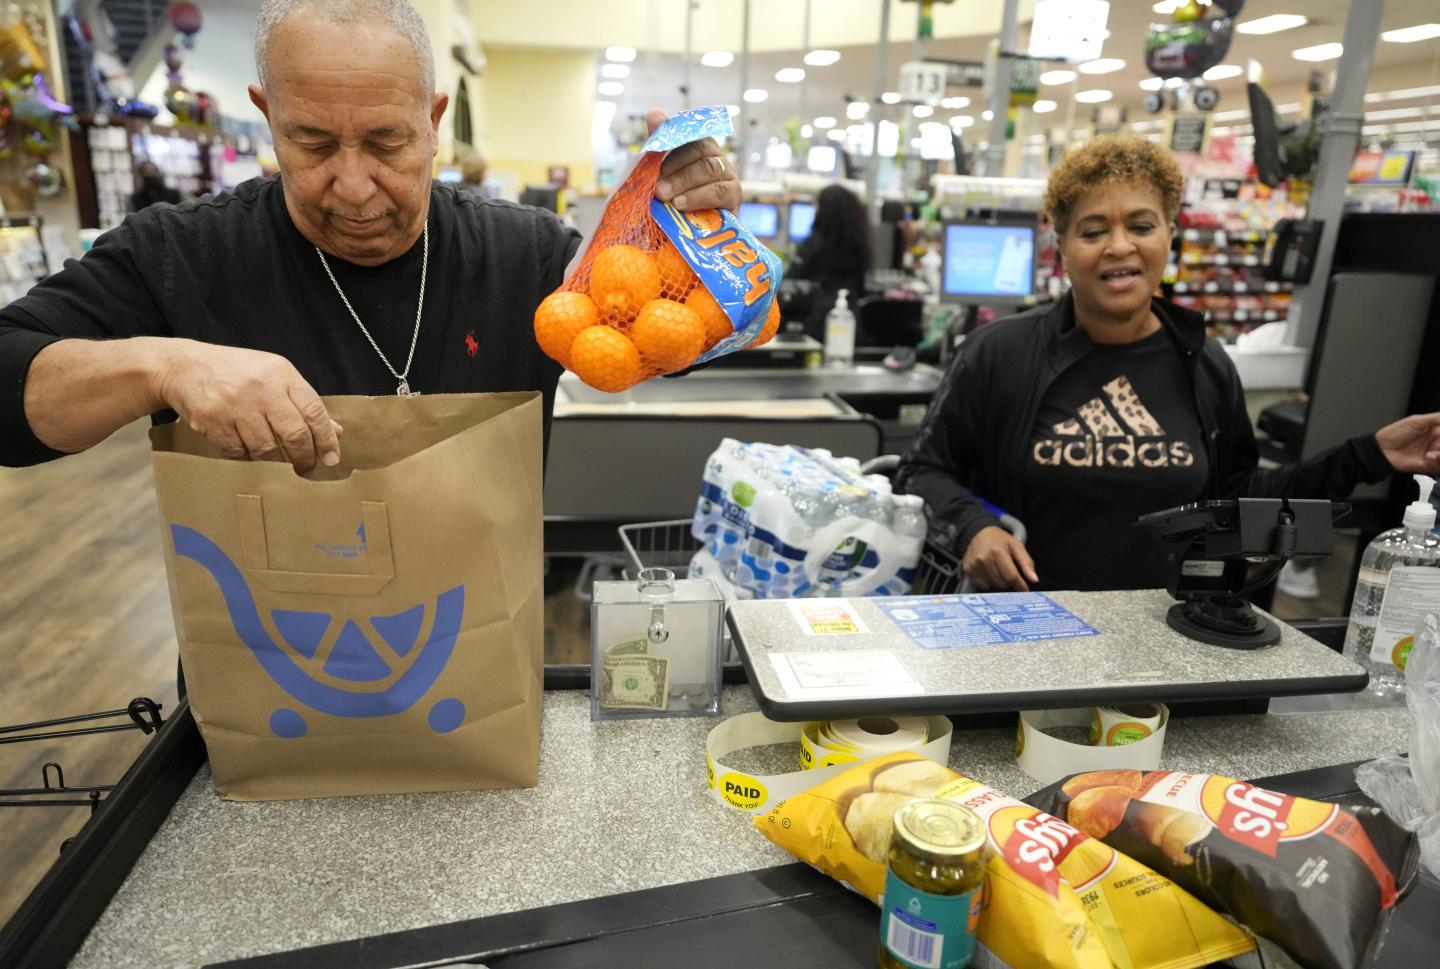
These types of purchases have become especially appealing for smaller, but necessary shopping trips. A Lending Tree survey of more than 6,000 U.S. consumers published in July found 29% of Americans self-report using buy now, pay later loans for groceries, nearly double the 14% from two years ago.
It’s all part of a bigger trend of buy now, pay later becoming an increasingly appealing option for consumers as they face an affordability crisis of increasing healthcare and childcare costs, as well as stubbornly high inflation, with 91.5 million Americans using apps like Klarna, Affirm, and Afterpay to finance purchases. Purchases with these apps grew 20% from 2021 to 2025, according to the Federal Reserve Bank of Richmond, though they still make up only about 1% of credit card transactions.
Researchers led by Panos Kouvelis, a professor of supply chain, operations, and technology at WashU’s Olin Business School, set out to find what exactly would make this model appealing to retailers, who have to pay merchant fee for each buy now, pay later transaction. The study authors developed an economic model that captured not only consumers’ willingness and ability to pay for goods using buy now, pay later, but also retailers’ expected profits. They found that retailers increased their sticker prices to offset the merchant fee, meaning in some cases, customers paying in-full effectively subsidized the customers who financed their purchases, and all consumers saw higher prices.
“Retailers, as a result of accepting these kinds of payments, they are going to increase prices, which basically means that all of us are going to pay for these practices that are out there,” Kouvelis told Fortune.
Why buy now, pay later might sting consumers and retailers alike
Retailers are feeling this pressure to raise prices particularly because of consumers’ growing reliance on loans to pay for basics like groceries. Buy now, pay later was originally intended for large discretionary purchases like furniture or gaming consoles. These products have higher margins, meaning that for the retailers selling them to consumers financing the purchase, they would still be profitable even after paying the merchant fee. Necessities like groceries, however, have much thinner margins.
A sign of economic strain for the consumer, this shift in how people are financing their purchases is also likely less appealing to retailers, who are pressured to raise prices to try to maintain tight margins on these necessities. If retailers are finding some goods are no longer profitable, they may stop stocking them, giving fewer choices to consumers.
“Why does it really make sense for the retailer,” Kouvelis said, “unless they are hoping that as a result you are buying a much larger basket of goods and therefore they are making money on other products.”
Buy now, pay later’s hidden dangers
There are broader concerns around consumers using buy now, pay later for basic purchases. This Fintech is largely unregulated and historically, these companies have not reported debt to credit agencies. As a result, there’s a growing pile of “phantom debt” for some consumers, who may carry five to 10 loans for buy now, pay later at a given time, Kouvelis explained. Lending Tree fund 47% of buy now, pay later users were late paying back a loan in the last year.
To be sure, this debt is not large, about $135 on average, and consumers are more likely to pay back debt from short-term financing first, but Kouvelis noted even without widespread economic impacts, the potential dangers of buy now, pay later are present for consumers and retailers alike.
“There is a certain fear,” he said. “There are some people that are living at the edge that are really overboring, and nobody knows about it. Of course, that’s bad for them because at some point time things are going to catch up with them …. For the retailers, if these people are coming your way and they’re lowering your margins, also they have an effect in terms of your profitability.”