Portugal. Friday, 25 June 2004. The sixty-fifth minute of the European quarter-final. Greece, 15/1 outsiders, versus France, the tournament favourites. Greece captain Theodoros Zagorakis floats a cross into the penalty area, a perfect arc slicing through the Lisbon air. Angelos Charisteas charges forward, soars above two towering French defenders, and thunders a header past the frozen goalkeeper into the back of the net.
Cue pandemonium. The underdogs, dismissed by every pundit, have taken the lead against all the odds. France, packed with stars like Zinedine Zidane and Thierry Henry, are stunned. They fight back, launching wave upon wave of attack, but Greece, grim and gritty, refuse to break. The final whistle blows and the defending champions are out: a result that shocks the football world.
But what happened off the pitch shocked me even more. The very next week, €10 billion was wiped off the French stock market. And no, France’s economic fundamentals hadn’t suddenly changed overnight. I was on the trading floor at Morgan Stanley and I saw it with my own eyes: some of the world’s supposedly smartest, most level-headed investors were visibly rattled. Their mood darkened; one trader stormed off and didn’t return for days. Their judgement wavered. The market cracked.
Sure, many things drive share prices: interest rates, energy costs, political turmoil — but all those factors are rational. They affect sales, profits, and dividends, so they should sway stocks. But watching traders react emotionally to a football game made me wonder: might markets also be moulded by mood?
After my summer in New York was over, I returned to MIT for the second year of my PhD in finance. It kicked off with a course on Empirical Asset Pricing. This was where we’d learn the supposed laws of motion for markets: the forces that govern whether stocks, bonds, and currencies rise or fall. But instead of animal spirits and human psychology, we were fed a diet of the Lettau-Ludvigson consumption-aggregate wealth ratio and the elasticity of substitution between durable and nondurable goods. According to these models, investors were coldly analytical robots, operating with laser-like precision and scrutinizing every shred of information that might give them an edge.
Yet I’d just seen something very different. Traders making decisions based not on data or fundamentals, but on whether their national team had won or lost. Sure, the France game was just one anecdote. But what if it wasn’t the exception? What if it was the rule? And so I asked a question that seemed absurd: could a football defeat sink a nation’s stock market?
I didn’t dare tell my professors what I was working on. MIT was the Vatican of mathematical finance. Steve Ross, one of its towering figures and heavily tipped for the Nobel Prize, was jetting around the globe giving keynotes on efficient markets, arguing that investors were both logical and lightning-fast at processing information. When I told my former colleagues at Morgan Stanley, they laughed it off. Surely Wall Street’s finest couldn’t be swayed by a football scoreline? Even the leading finance textbook of the time, Principles of Corporate Finance by Brealey, Myers, and Allen — which I’d studied as an undergrad and which sat on every banker’s shelf — relegated psychology to a lonely subsection of a solitary chapter, and bluntly dismissed its relevance.
Undeterred, I hunted down data on 750 games across thirty-nine countries, crunched the numbers, and discovered an unmistakable pattern: stock markets consistently fell after the national team lost a match. Yet even as the evidence stared back at me, I was sure no one would believe it.
Eventually, I had to present my findings at a PhD seminar. I braced for humiliation, especially when I spotted professors slipping into the room. It was rare for faculty to turn up to a student talk and I was sure they’d come to watch a train wreck. But they listened with an open mind and, to my relief, were generous with their praise afterwards. The paper was eventually published in the Journal of Finance, the top outlet in the field, and was a finalist for its best-paper prize. To my astonishment, the story burst out of academia. I soon found myself on CNBC, ESPN, and Sky Sports, and in the Wall Street Journal, Financial Times, and The Times.
That study opened my eyes to a whole world of research — wacky and innovative, yet rigorous and robust — showing that even the most rational minds fall prey to emotion. Investors, for all their spreadsheets and sophistication, are human. And humans all over the world slip into the same expensive traps, causing most to flounder while a savvy few cash in on the chaos. The impact of psychology on the markets is now mainstream. A few editions later, Brealey-Myers-Allen became Brealey-Myers-Allen-Edmans, and now grounds itself in how finance actually works in real life.
The early embarrassment that I feared developed into a new lens on the financial world, one that embraces human nature rather than denies it. That lens helps us to see the world more clearly and to act more shrewdly, by avoiding our own mistakes and exploiting those of others. It’s not only theoretically intriguing, but practically actionable.
There’s a popular idea, made famous by books like The Wisdom of Crowds, that collective intelligence leads us to the truth. I might be bullish on Tesla because I’m an Elon Musk fanboy; you might be bearish because you can’t stand his politics. Our biases cancel out, and the market reflects reality. That’s the theory. Yet it only works when errors are evenly spread — like a county fair where people guess the weight of an ox, the opening example in that book. Some go too high, others too low, and when you average it all out, you land close to the mark.
But markets aren’t county fairs. No one gets emotionally attached to the weight of an ox. On the trading floor, impulses run deep and when they hit, they push everyone the same way. After France’s shock defeat in Euro 2004, French investors were deflated, demoralized, and dejected en masse, and the market took a dive.
Worse, we don’t make decisions in a vacuum. At the fair, you guess the weight on your own and submit it in secret. But markets are a different beast. We’re constantly looking over our shoulders, wondering what others know that we don’t, seeing how they act, and fearing that we’re missing out. If we see Bitcoin skyrocketing, we don’t want to be the idiot late to the party — so we buy in too. That pushes the price even higher, tempting more people to join the frenzy. And just like that, the mania goes viral.
That’s what this book is about. The mistakes investors make and why they make them. How those blunders don’t cancel out but snowball into booms and busts. How they spread like viruses through financial markets and ripple from Wall Street to Main Street. How to avoid getting infected — or, better still, how to spot others’ missteps, recognize when the market has lost its mind . . . and profit from the madness.
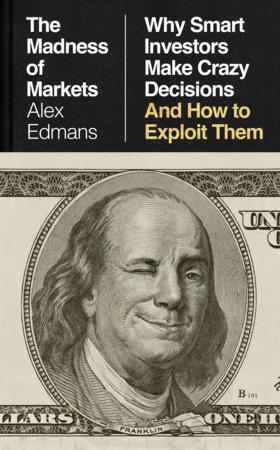
Excerpted from The Madness of Markets, in agreement with Crown Currency, an imprint of The Crown Publishing Group, a division of Penguin Random House LLC. Copyright © 2026 by Alex Edmans.