Good morning. We gave the newsletter a little visual zhuzh over the weekend.
In honor of our new look, I thought I’d change up the format, too. A nip here, a tuck here, and—as always—blissfully brief.
Hope you like it. (Shout if you don’t.) —Andrew Nusca
Thoughts? Suggestions? Hot tip? Drop me a line.
THE BIG STORY
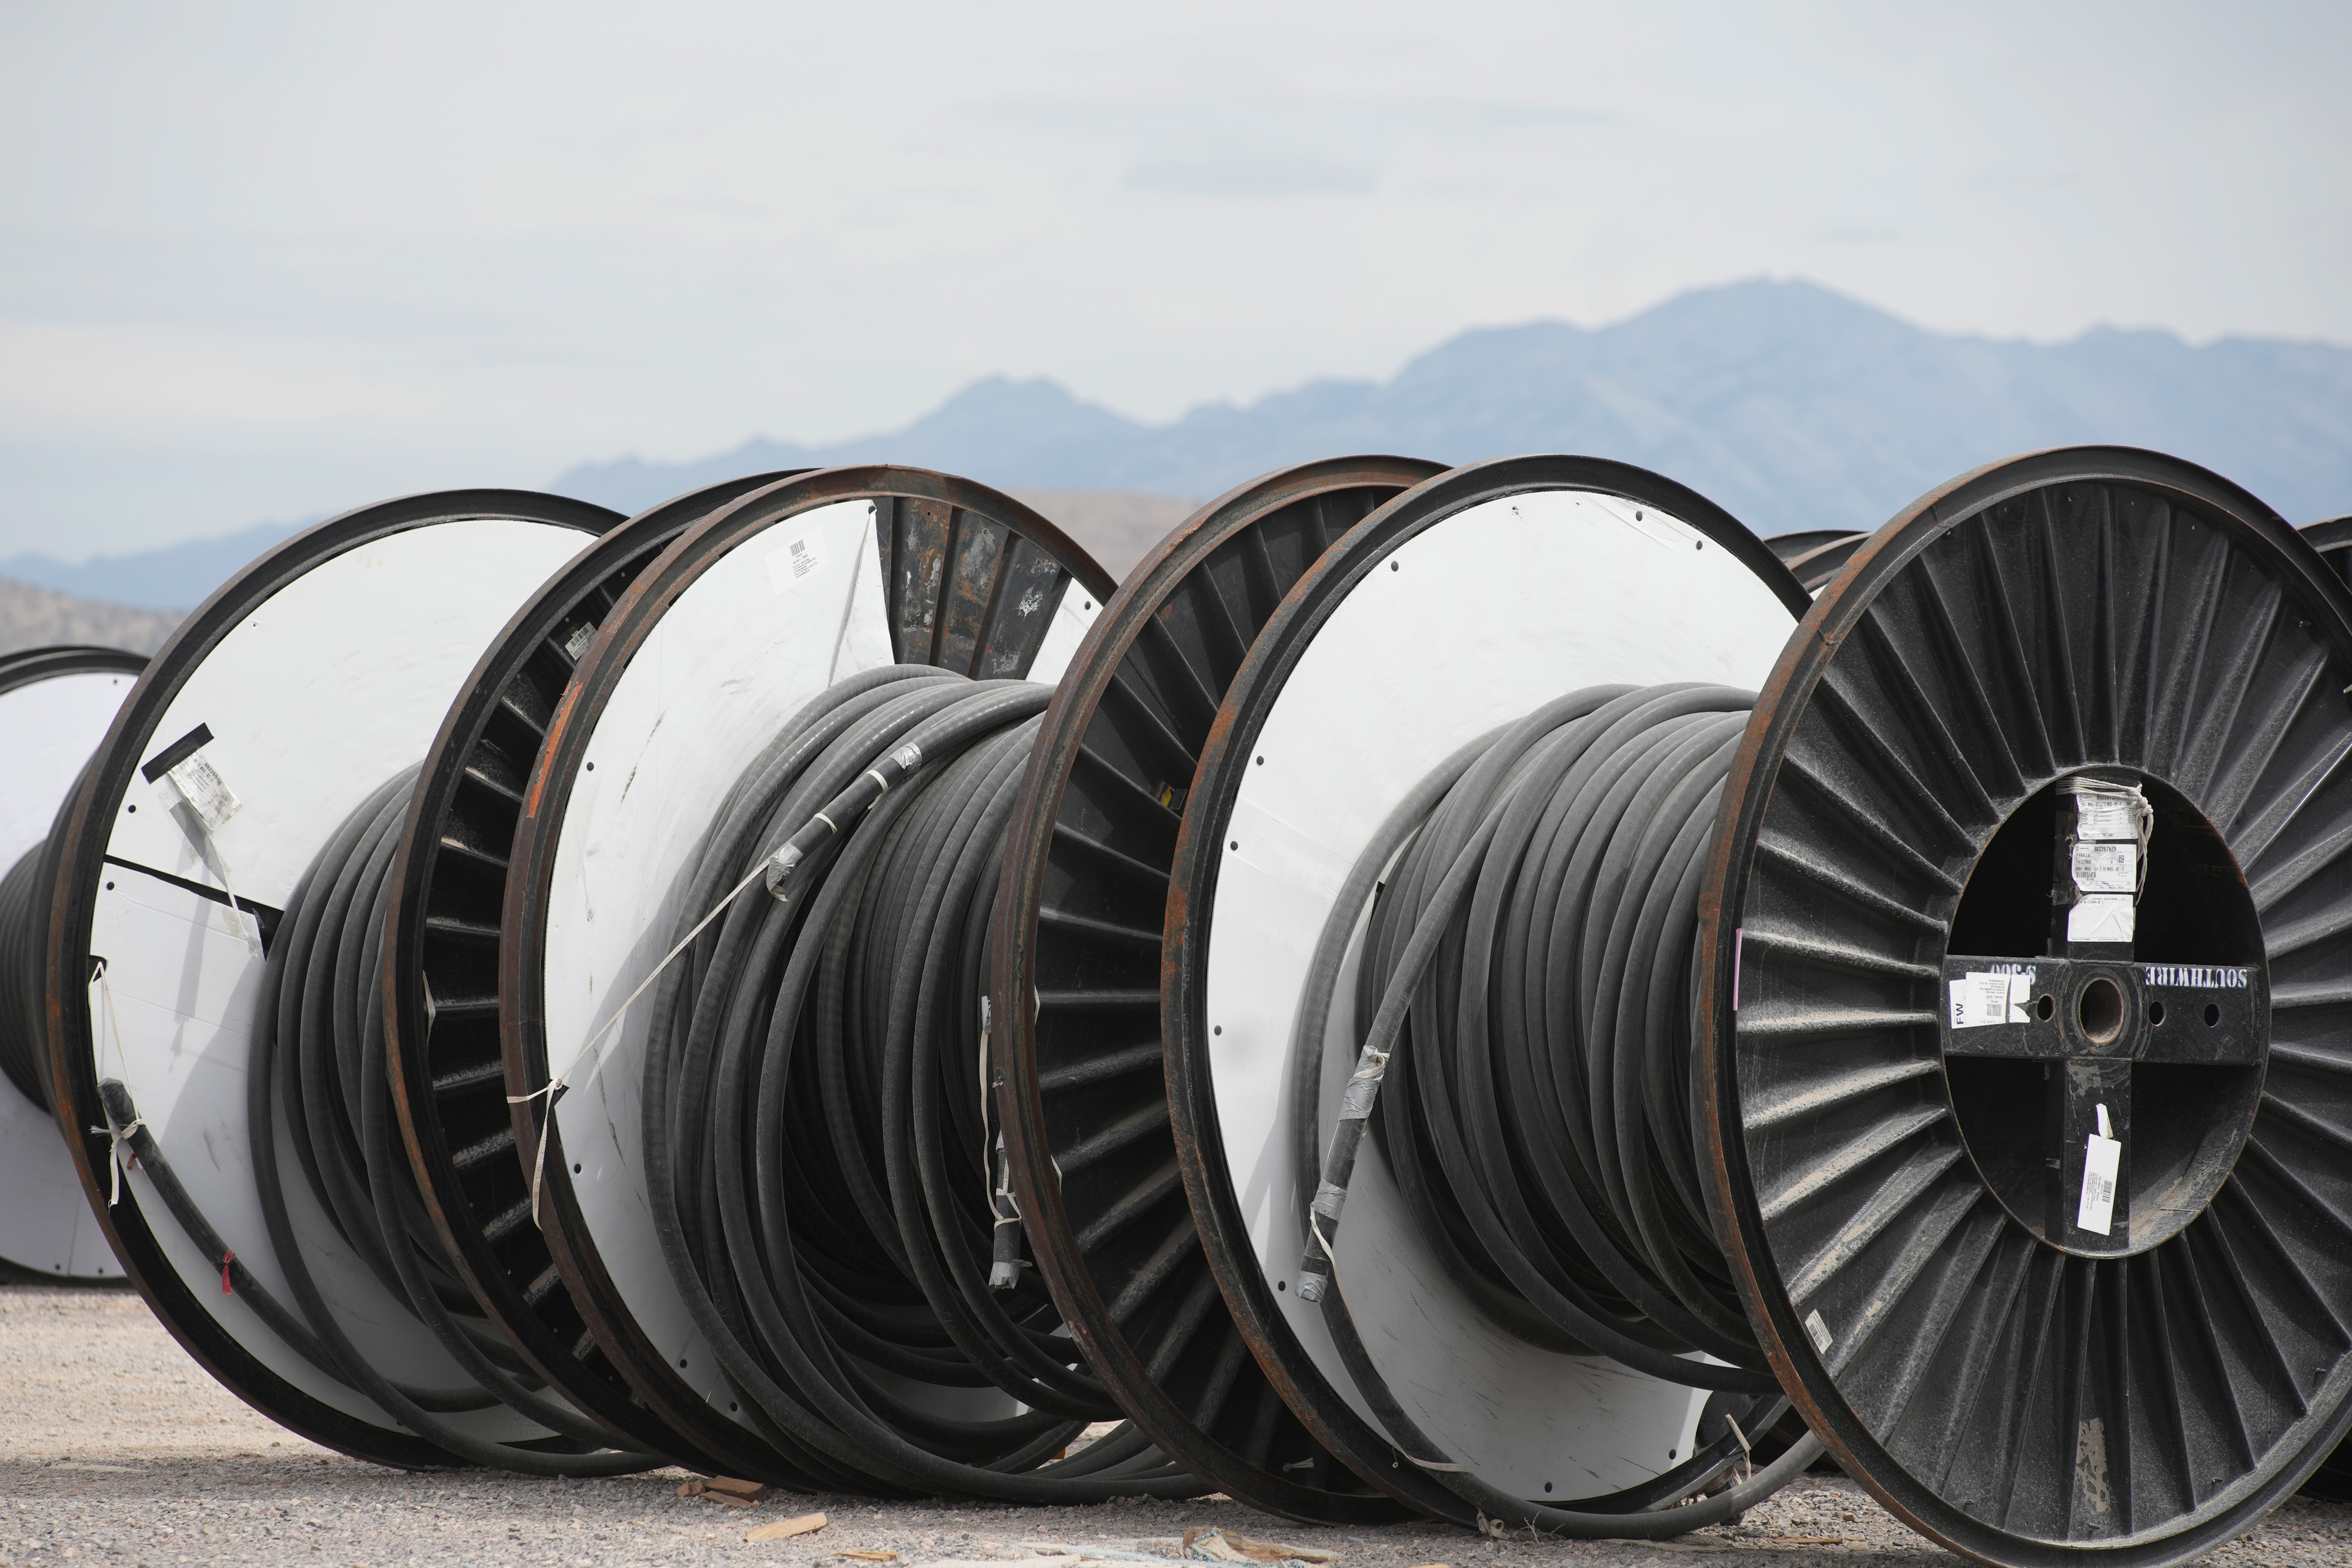
U.S. spending on data centers and IT now exceeds housing
Two decades after the housing boom reshaped, then tanked, the U.S. economy, the AI boom is similarly transforming the drivers of growth.
Hyperscalers have poured so much money into building as much AI infrastructure as possible—and as quickly as possible—that investment from a handful of companies is expected to reach $1 trillion a year soon.
Meanwhile, the housing market has been largely frozen since the COVID-era boom ended in 2022, when the Federal Reserve embarked on an aggressive rate-hiking campaign to rein in inflation.
“We’re seeing a pivotal shift in the U.S. economy: investment is shifting away from residential investment and towards computers,” Adam Shapiro, vice president at the San Francisco Fed, posted on LinkedIn recently.
He pointed out that inflation-adjusted spending on information processing equipment, which includes data centers and computer hardware, now exceeds residential investment.
According to data from the Bureau of Economic Analysis, real private residential fixed investment was $748 billion in the second quarter, down 18% from an early 2021 peak. During that same span, spending on information processing equipment has soared 51% to $752 billion.
“The AI investment boom is massive,” Shapiro added.
The onslaught of AI spending is expected to keep ramping up. S&P Global estimated last month that capital expenditures from Alphabet, Amazon, Microsoft, Meta, Oracle, and SpaceX will exceed $1.3 trillion in 2027, up from a projected $870 billion in 2026 and $470 billion in 2025.
The ratings firm added that the industry’s capex is growing faster than revenue, warning that the aggressive build-out could lead to overcapacity if future demand doesn’t pan out as expected.
S&P sees 2028 as an inflection point, with revenue accelerating and capex flattening. Until then, it added, operating cash flow from the six hyperscalers will collectively be negative in 2026 and 2027. —Jason Ma
THE BLIND BOX
“Indiscriminate digital expansion has weakened learning environments rather than strengthened them.”
THE RUNDOWN
—A jailbreak dispute led White House officials to order Anthropic to take Fable offline.
—SoftBank entertains one of the biggest junk bond sales ever by exploring issuing more than $11 billion in debt for its OpenAI investment.
—Apple lays off staff for Fitness+, its subscription workout media service.
—Alibaba releases Qwen-Image-2.1, an open-weight image generation model it says outperforms most closed-source competition.
—Is AI actually improving health care? Reply hazy, try again.
—People in China launched more than 7 million one-person startups last year.
—Polymarket’s CEO reportedly waved off an active fraud scheme in a bid to prioritize the company’s growth.
—Coming soon to the U.S. federal government: A new AI czar and an “AI Force.”
THE PARTING SLOP
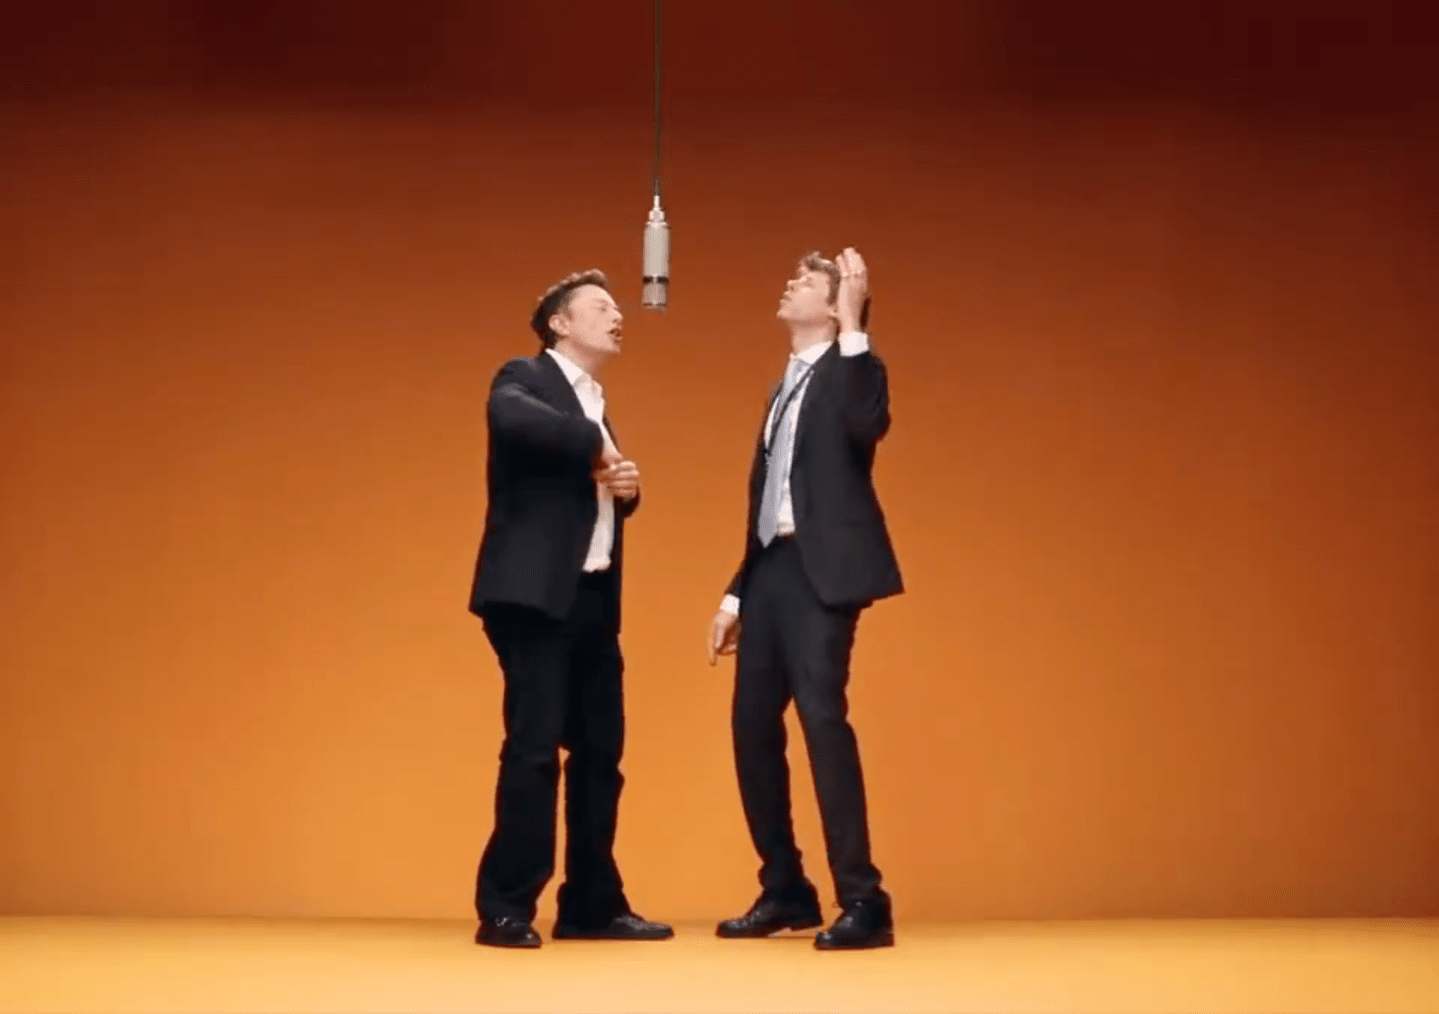
What if Elon and Sam set aside their differences to become a trap act? Now you know.