Federal Reserve Chair Kevin Warsh has revealed himself. If not a card-carrying monetarist, he is at least a camp follower. This represents a dramatic change at the Fed, where the past Chairman Jerome Powell repeatedly rejected the basic tenets of monetarism.
This is a welcomed earthquake. After all, there are almost no monetarists left in the world (except for us, and we’ve been fighting a lonely rearguard action for over 40 years). The Federal Reserve has rejected monetarism consistently — and on the record — because it preferred other models for understanding the economy. In academia, monetarism has been out of fashion for decades. But by his own words, a monetarist is now leading the central bank.
Just what is monetarism? It’s a doctrine which holds that money has a major influence on both the level of asset prices, economic activity, and the price level. Any discussion of national income determination must, therefore, center on the quantity of money and the banking system, since banks produce most of the money in modern economies. When it comes to monetary policy, its objectives are best met by targeting the rate of growth of the money supply.
Today, most economists pooh-pooh monetarism. Money and banking are nowhere to be found in their macroeconomic models, or their discourses about the course of asset prices, economic activity, and prices. Indeed, their forecasting exercises are typically based on elaborations of Keynesian income-expenditure models that exclude money and banking.
If that’s not enough, we think that the Fed’s backroom staff, mostly Keynesian-leaning Democrats, don’t want alignment with a philosophy usually affiliated with Milton Friedman, but that’s another story. Just look at what Joe Biden said in 2020 about how the dean of monetarism wasn’t “running the show anymore.”
This, of course, is why today’s mainstream economists failed to anticipate the post-COVID burst of inflation in the U.S. and elsewhere. It is also why, during the then-evolving Great Financial Crisis, Queen Elizabeth, on a November 2008 visit to the London School of Economics, asked, “Why did nobody notice it?”
Well, it turns out that a tiny band of monetarists, including ourselves and Tim Congdon, did notice the Great Financial Crisis. We also anticipated the post-COVID surge in inflation. Never mind. What about Chairman Warsh?
Kevin Warsh has not swallowed the economic profession’s entrenched non-monetary ways of thinking. Like a jack in the box, Warsh has sprung out as a monetarist. Warsh first let the cat out of the bag in August at the Fed’s Jackson Hole Symposium, when he enunciated a set of principles that included the idea that changes in the money supply had something to do with economic activity and inflation.
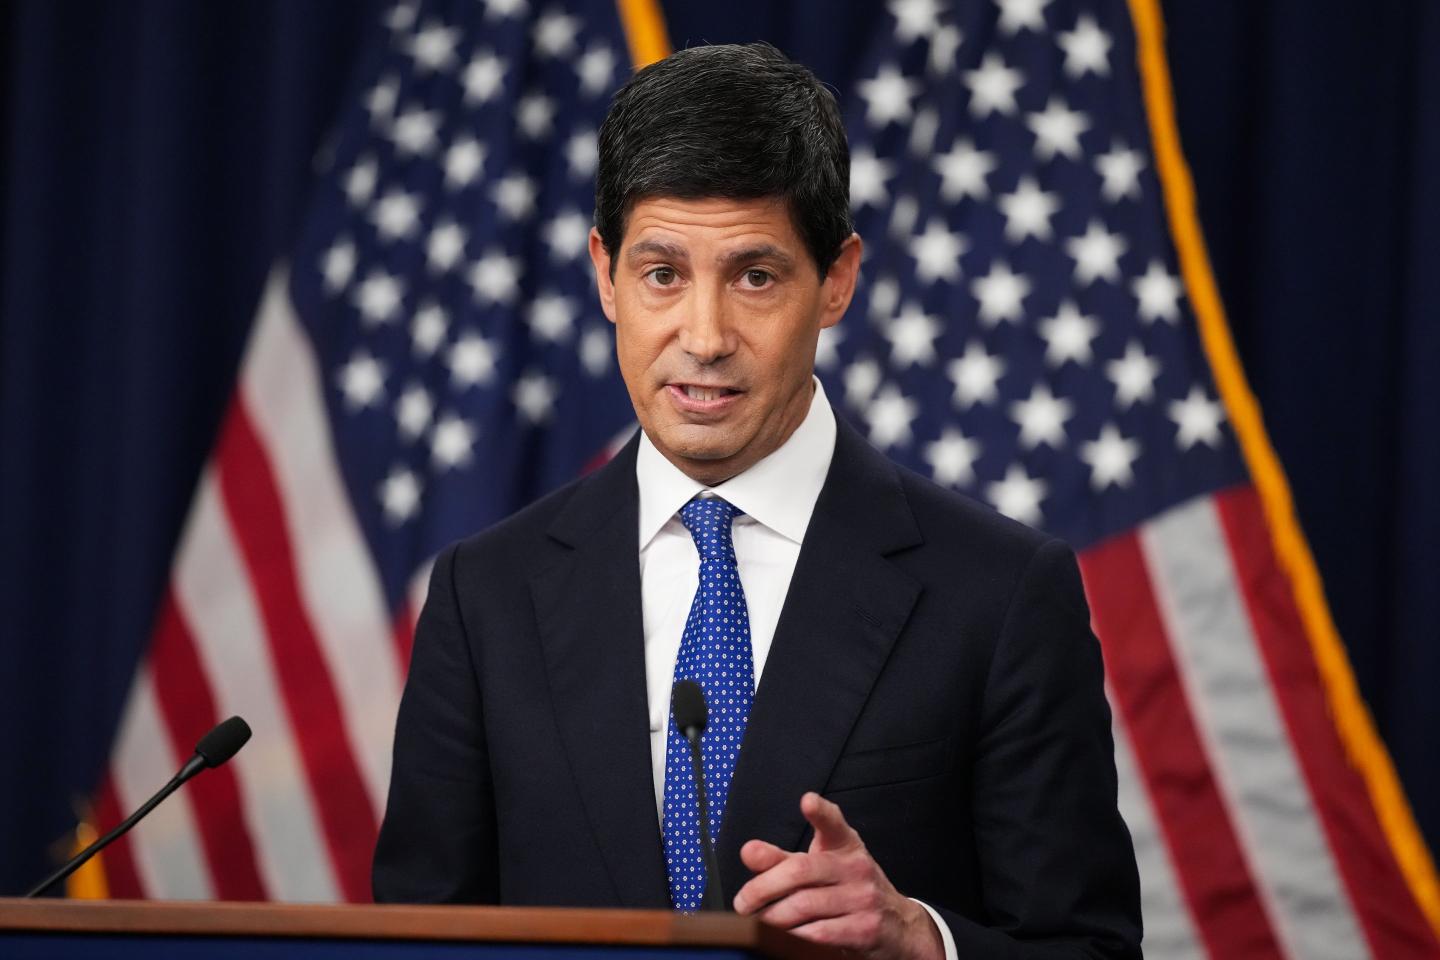
On September 16, during his post-Federal Open Market Committee (FOMC) press conference, Warsh further elaborated.
First, Warsh used the language that monetarists like to use about individual price changes and inflation. Higher energy prices or food prices do not “cause” inflation. Indeed, Warsh said the Fed cannot address any individual prices, like those for food and energy, but that the Fed can ensure that those relative price changes do not have second and third order effects. In other words, the Fed is responsible for overall price changes, not relative price changes.
As monetarists, we would go a step further. Unless there has already been excess money growth over the preceding year or so, relative price changes cannot translate into sustained changes in the overall price level. For this reason, we tend to discount the validity of discussions about second or third round effects.
Second, when asked about how the Fed’s rate hike would affect lower income groups in the US, Chairman Warsh said the Fed does not deal in questions of distribution. The Fed looks at aggregates like the labor market, GDP, total spending, and overall inflation. Having said that, he conceded that the lowest income classes — those without financial assets and those who tend to live from paycheck to paycheck — would benefit most from stable prices. That was a monetarist response.
Third, when asked if the most recent CPI data had influenced the Fed’s decision to raise rates, he said that was not the case. “Datapoints are noisy”, he argued. What mattered was the trend, and the trend of inflation was still too high.
Warsh’s response accords precisely with the monetarist view that short-term forecasts of inflation are simply not feasible. There is too much noise in the data. Monetarist analysis can provide a range or channel for price levels (or inflation) over a 1- to 3-year horizon, but not a month-to-month forecast.
Fourth, when asked about the level of the Federal Funds rate relative to its “neutral” rate (or r*), Warsh replied that as a student of economics he had studied the neutral rate, or what is called the Wicksellian real rate, after Swedish economist Knut Wicksell. The concept, he declared, was of academic interest but had no bearing on the Fed’s practical decision-making.
Again, this comports with monetarist views on interest rates. Administered rates such as the fed funds rate and short-term market interest rates can be both a driver of future money growth and a consequence of prior monetary growth. For example, if the money growth rate doubles, the first effect is lower rates, but then, as the economy recovers, the demand for credit increases and inflation rises, the second effect is an increase in rates. This is exactly what happened during and after the COVID pandemic.
Because changes in broad money growth have this two-stage effect on interest rates, it makes no sense to rely on a Wicksellian framework of equilibrium or neutral interest rates. The Quantity Theory of Money, however, provides a fairly precise guide to the appropriate rate of money growth for an economy. It is therefore always better to rely on the rate of broad money growth as a better guide to the stance of monetary policy than on the abstract, non-measurable concept of an equilibrium interest rate.
On at least two occasions during Warsh’s September 16 press conference, he said that he would have been hard-pressed in recent months to describe financial conditions as restrictive. Judging the level of interest rates against an unobservable “neutral” rate would clearly have been challenging. Instead, although he did not say so, the rather high rate of broad money growth over the past 6-9 months would have provided a clearer metric on the state of monetary and financial conditions: the rate of broad money growth in the range 6-8% has clearly been too high. To hit the Fed’s target rate of inflation of 2% the rate of growth in the money supply needs to be reduced to around 6%.
After a shaky start with his first two press conferences, Chairman Warsh is clearly gaining confidence as he starts to articulate a framework that is consistent with monetarism. It promises to be a seismic shift for the Fed.
The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.