More than half of Gen Z, 51%, say AI poses the greatest threat to their job security, according to an iCIMS Workforce Report. That anxiety persists even as 87% of Gen Z workers already use AI for professional purposes, and even as 24% say folding AI into their daily work has led to burnout, according to a new Robert Half survey.
The same generation that names AI as its biggest professional threat is also the most willing of any to hand it real power over its money. In Betterment’s 2026 Retail Investor Survey—1,000 U.S. investors fielded in late March—48% of Gen Z investors say AI has already influenced a financial decision they made, and 41% say they’re comfortable using AI for long-term financial planning. Among Baby Boomers, both figures sit at 5%.
Once you isolate people who already pay for human advice, AI has an even greater influence. Betterment Advisor Solutions’ 2026 survey, fielded in June among 1,001 people with a standing advisor relationship, found 65% of Gen Z clients say AI has influenced a decision they wouldn’t otherwise have made—the highest of any generation, well above the 24% figure among retail investors with no advisor at all. These are people already paying a human for judgment. Most are still letting the algorithm they say might end their career quietly co-sign their portfolio.
“Investors want more ways to understand and engage with their finances, but they also need help turning all that information into decisions,” Devon Klumb, a CFP at Betterment, told Fortune.
Not hypocrisy so much as bad instruments
It would be easy to call this hypocrisy and move on. But a closer read of the underlying research suggests something more structural: Gen Z isn’t knowingly contradicting itself, it’s triangulating with instruments it doesn’t fully trust.
Charles Schwab’s Modern Wealth Survey found Gen Z begins investing at 19 on average, 16 years earlier than Baby Boomers did at 35, and 48% say they learn about investing primarily from social media. But they know not to trust influencers: when asked who they actually trust with financial guidance, Gen Z ranks parents and financial professionals above social media, not below. They’re sourcing decisions from channels they don’t believe, for lack of a better one immediately at hand—and AI tools, with their fluent, confident-sounding output, fill that gap whether or not they’ve earned the trust.
Andrew Lendnal, head of financial wellness at Wealthspire, said it’s more than “hypocrisy”: “Young adults don’t have an information problem. They have an information quality, trust and decision-making problem,” he told CNBC. It isn’t that Gen Z fears the algorithm and defers to it anyway out of impatience—it’s that confident-sounding output has quietly become a stand-in for judgment nobody taught them how to exercise on their own.
There’s a name for the broader pattern, and it predates Gen Z entirely. Researchers call it the AI “trust paradox“: people’s willingness to use AI-enabled tools consistently outpaces their actual trust in them, a gap driven by FOMO, optimism that the tools will keep improving, and a bet that the efficiency gain outweighs the risk.
Same tech, different tab
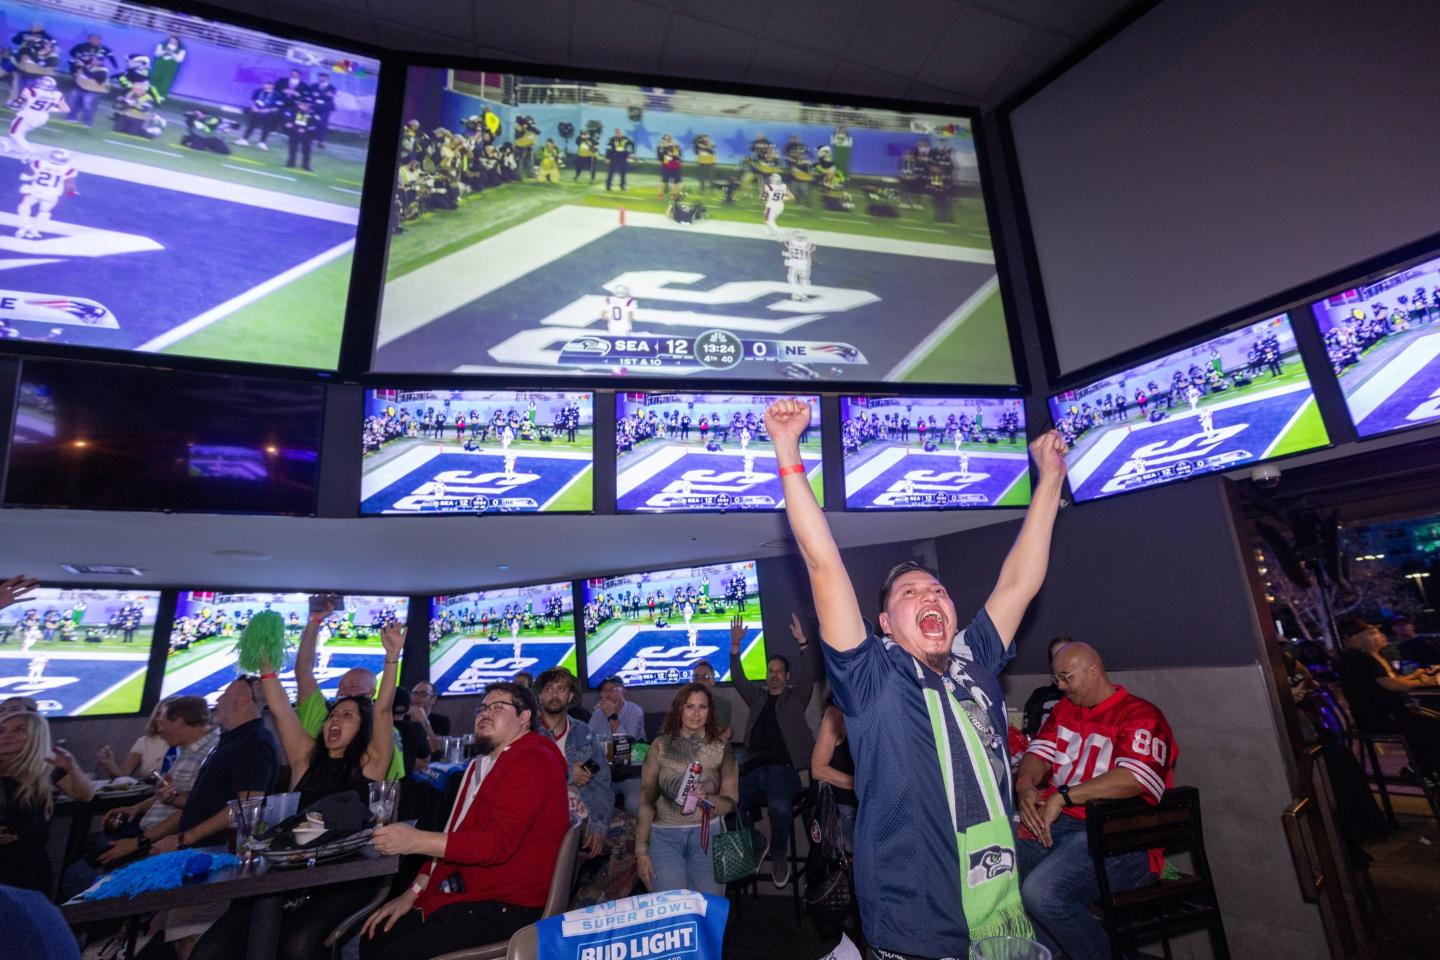
One way this contradiction is displayed by the generation is through what they see as investments. Sportsbooks have leaned into generative AI for exactly this audience: personalized odds, tailored previews, and prop suggestions tuned to a user’s betting history. A cottage industry of standalone AI betting copilots like PropGPT, PropsBot, and Gambly now performs for gamblers roughly what a robo-advisor performs for investors: give a confident-sounding recommendation based on data and remove the friction of deciding alone.
That appetite for a faster payout shows up in where the money moves. In Betterment’s retail survey, 52% of Gen Z investors say they redirected money originally set aside for investing into sports betting at some point in the past year, and 14% do so multiple times a month. More than a quarter, 26%, describe sports betting as part of a deliberate, ongoing financial strategy, compared with 14% of Millennials, 6% of Gen X, and 1% of Boomers.
But with this comes very real implications: the New York Fed has linked the spread of legalized sports betting to rising delinquency and bankruptcy rates in the states that adopted it earliest, and a 2025 U.S. News survey found a quarter of sports bettors missed a bill because of wagers, with 30% taking on debt to fund betting. Sports betting has grown into a nearly $17 billion industry in the U.S., up from about $400 million in 2018, with bettors of every generation recovering less than 75 cents for every dollar they put in.
Dan Egan, Betterment’s VP of behavioral finance and investing, draws the line Gen Z keeps blurring. “The fact that young people are sports betting isn’t necessarily a negative thing, as long as they are budgeting it as entertainment,” Egan told Fortune. “However, the fact that some are starting to think of gambling as a way to build wealth is very concerning. Sports betting and investing may look similar on the surface, but they’re fundamentally different: investing puts money into assets that can create value and appreciate over time, while betting is a negative-sum game where the house takes a cut.”
“If younger investors are looking for ways to get ahead faster, the most valuable thing they can invest in is themselves, their skills, careers and earning potential. A bet ends when the game does; a real investment can compound for years.”